Ours had a supplement, but it was high cost..
Social Security
T
W
Ours had a supplement, but it was high cost..
What's high? I'm not too familiar with the cost of these plans.
We pay $200 a month for full coverage when you retire, goes to $100 when you go on medicare. Same plan as if you were still working with $1000 a year deductible. They have a enhanced-no deductible medicare plan for $200.
You know everything Dave give him some answers.
Actually im trying to find out some answers for myself, when the time comes.
T
Was about 200. So I went with an advantage plan. Problem is if you start out that way, as I did, you are stuck, because now I can't switch to a supplement for either of us because of health conditions.
T
What's high? I'm not too familiar with the cost of these plans.
We pay $200 a month for full coverage when you retire, goes to $100 when you go on medicare. Same plan as if you were still working with $1000 a year deductible. They have a enhanced-no deductible medicare plan for $200.
I thought 200 was high. But I guess it is really not now. I paid 200 also til 65. Then forced onto medicare. I never saw any plans offered except the one supplement. But as always, I could be wrong. ..I didnt think we would need more than just basic, because we were mostly healthy.. I was wrong, lol
Our retiree insurance is pretty much like Teamcare other than the out of pocket premium $150/300 per month (from UPS, not the union though). Then at 65 we have to switch to Medicare and the union is done with us.
I get mail from some Teamcare supplemental, but after Teamcare tried to screw me out of $93,000 a few years ago they can just kiss my ass. My wife is disabled being legally blind. She is two years younger than me. Teamcare told us back when she was diagnosed in 1999 she could stay on Teamcare since it was better than Medicare at the time. Once I turned 65, she was no longer qualified for Teamcare under newer rules. So even though they pre-approved doctor visits and a couple of out-patient surgeries they went back and we were billed for two years worth of care. Teamcare took that money from doctors bank accounts so we had a dozen doctors demanding to be paid. It took me two appeals working with Local 728 to win. The second appeal I won because we filed on every individual bill and Teamcare could not produce a letter that I was supposed to sign saying I was aware of those changes being made. So I won on a technicality. Not your usual case for most people. I would recommend to all new retirees to go down to your Local and talk directly to the person in charge of benefits. I gifted Rosemary at Local 728 with a very nice cutting board for her help.
Wally, I don't know your age, but make sure you sign up for Medicare a few months before you turn 65 or you will have to pay a higher rate. That is very important. Also, ignore all those phone calls and garbage you will get in the mail about picking a certain insurance company on your own. Find a local Medicare Advisor. They get their commission from Medicare, not an insurance company. They will ask you for all the medications you take and which doctors you use. Then compare all your options. In my case, the Aetna Advantage plans work best for us. There are three different ones we looked at. You have to sign up in the Fall every year so you can change anytime. We picked one that is going to save some money over last year. My dental is going up from $2100 to $3000. Primary doctor visits have no co-pay, but my specialist co-pays will drop from $55 to $39. My personal experience with anything that has the Teamster name in it is not a good deal. I went insurance shopping a few months ago when I got a newer car. Farmer's Insurance supposedly had a special rate for Teamsters and Retirees but that agent tried to charge me a thousand bucks a policy over what I was already paying. Like anything else, shop around and compare.
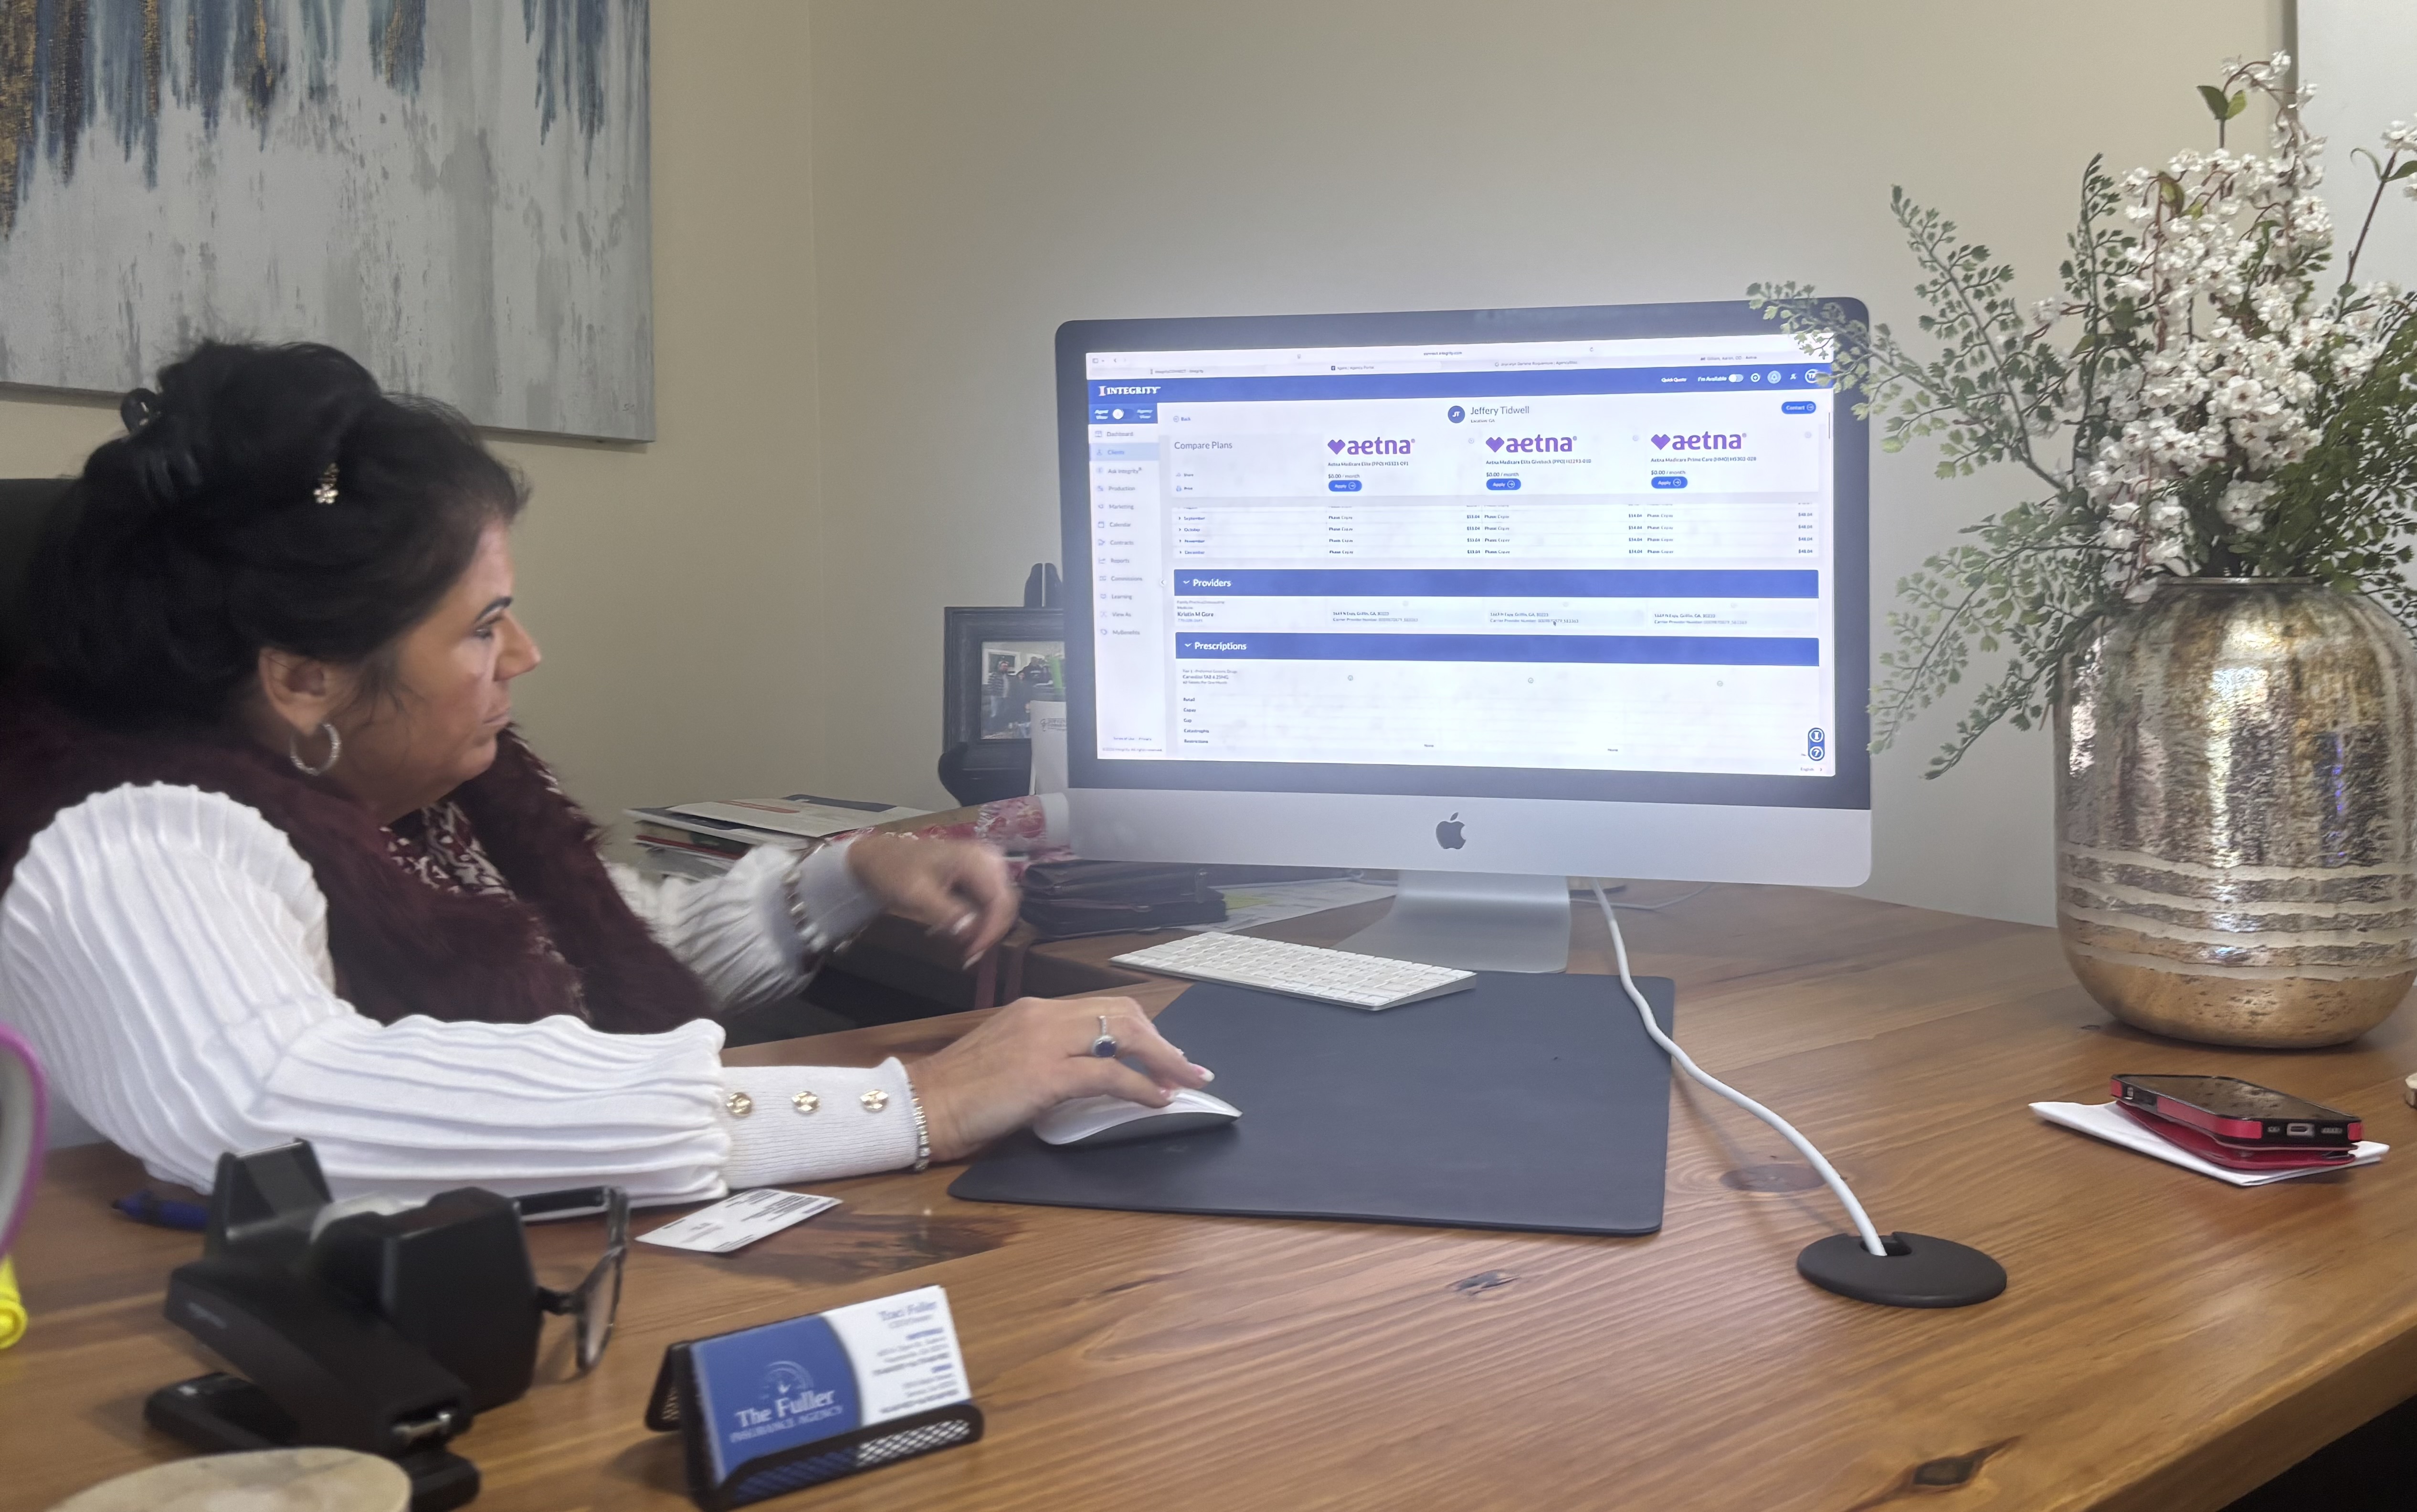
Wally, I don't know your age, but make sure you sign up for Medicare a few months before you turn 65 or you will have to pay a higher rate. That is very important. Also, ignore all those phone calls and garbage you will get in the mail about picking a certain insurance company on your own. Find a local Medicare Advisor. They get their commission from Medicare, not an insurance company. They will ask you for all the medications you take and which doctors you use. Then compare all your options. In my case, the Aetna Advantage plans work best for us. There are three different ones we looked at. You have to sign up in the Fall every year so you can change anytime. We picked one that is going to save some money over last year. My dental is going up from $2100 to $3000. Primary doctor visits have no co-pay, but my specialist co-pays will drop from $55 to $39. My personal experience with anything that has the Teamster name in it is not a good deal. I went insurance shopping a few months ago when I got a newer car. Farmer's Insurance supposedly had a special rate for Teamsters and Retirees but that agent tried to charge me a thousand bucks a policy over what I was already paying. Like anything else, shop around and compare.
No one plan is right for everyone. A lot depends on your health and what medications you take. Many Advantage plans don't cover dental or charge you extra so that is something to look at. And even if you do find a good plan that one may not be offered the next year. I would like to find a plan, set it, and forget about it but unfortunately you can't do that.
W
Wally, I don't know your age, but make sure you sign up for Medicare a few months before you turn 65 or you will have to pay a higher rate. That is very important. Also, ignore all those phone calls and garbage you will get in the mail about picking a certain insurance company on your own. Find a local Medicare Advisor. They get their commission from Medicare, not an insurance company. They will ask you for all the medications you take and which doctors you use. Then compare all your options. In my case, the Aetna Advantage plans work best for us. There are three different ones we looked at. You have to sign up in the Fall every year so you can change anytime. We picked one that is going to save some money over last year. My dental is going up from $2100 to $3000. Primary doctor visits have no co-pay, but my specialist co-pays will drop from $55 to $39. My personal experience with anything that has the Teamster name in it is not a good deal. I went insurance shopping a few months ago when I got a newer car. Farmer's Insurance supposedly had a special rate for Teamsters and Retirees but that agent tried to charge me a thousand bucks a policy over what I was already paying. Like anything else, shop around and compare.
Not there yet but we saw an advisor before I retired and he said to take traditional Medicare since the union coverage becomes the secondary, plus full prescription, dental and vision.
The IRRMA will be hefty with wifey earnings, but what can you do?
Not there yet but we saw an advisor before I retired and he said to take traditional Medicare since the union coverage becomes the secondary, plus full prescription, dental and vision.
The IRRMA will be hefty with wifey earnings, but what can you do?
IRMAA isn't forever if your income changes. It has a 2 year look back. You can appe8 it later of your income is lowered
IRMAA isn't forever if your income changes. It has a 2 year look back. You can appe8 it later of your income is lowered
It should change automatically if your income changes. It can get tricky trying to stay under the threshholds where they have huge jumps in cost.
It should change automatically if your income changes. It can get tricky trying to stay under the threshholds where they have huge jumps in cost.
I shouldn't have that problem

Log in to reply.